
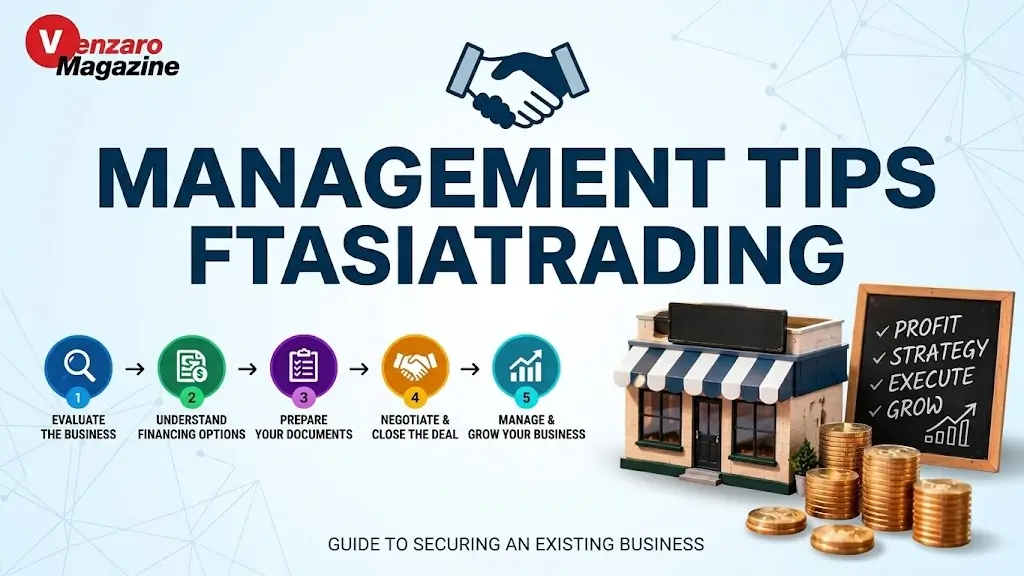
Effective management is about more than keeping tasks organized or making quick decisions. It involves setting clear goals, using resources responsibly, communicating effectively, and building consistent habits that support long-term progress. The keyword Management Tips ftasiatrading relates to these ideas, particularly in the context of trading-related activities, financial awareness, business organization, and disciplined decision-making.
For readers exploring this topic, the most useful approach is to focus on practical management principles rather than expecting a single technique to guarantee success. Whether someone is learning about business operations, organizing a small team, or trying to understand how disciplined planning applies to financial markets, a structured approach can make complicated decisions easier to evaluate.
FTAsiaTrading appears online in connection with financial, business, and trading-related educational content. However, the keyword alone does not establish that a particular company, regulated financial service, or proprietary management system exists. It is therefore helpful to separate general management guidance from claims about any specific platform.
This guide explores the principles behind effective management, explains how to organize work and evaluate decisions, and highlights common mistakes that can undermine progress. It also considers how these principles apply to trading-related situations without promising financial returns or treating uncertain outcomes as predictable.
What Does Management Tips ftasiatrading Mean?
Management Tips ftasiatrading is a search phrase associated with advice about organization, planning, decision-making, and managing trading-related activities. Readers may use it to find information about improving operational efficiency, developing disciplined habits, or understanding how management principles can support better financial decisions.
The phrase can be understood through three connected areas.
Personal management involves controlling your time, setting priorities, keeping records, and following a consistent decision-making process. These habits help individuals avoid unnecessary distractions and make their goals easier to evaluate.
Business management focuses on organizing people, processes, budgets, responsibilities, and performance. A well-managed business makes it easier to identify problems, distribute work, and respond to changing circumstances.
Trading management involves planning financial decisions, understanding potential losses, keeping track of exposure, and reviewing results. Unlike ordinary task management, trading introduces market uncertainty, so careful planning cannot guarantee a positive outcome.
Understanding these differences helps readers choose advice that matches their actual needs. A business owner may benefit most from clearer responsibilities and operational planning, while someone studying financial markets may need a better understanding of uncertainty, risk, and record keeping.
Why Effective Management Matters
Good management provides a framework for making decisions consistently. Without one, people may change priorities too frequently, overlook important information, or react to immediate pressure instead of considering their longer-term objectives.
It Creates Clear Direction
Goals provide a reference point for deciding what deserves attention. When objectives are vague, it becomes difficult to distinguish meaningful progress from activity that simply keeps people busy.
A practical goal should explain what needs to be accomplished, why it matters, and how progress will be evaluated. For example, a small business might aim to reduce order-processing errors by reviewing its procedures and identifying recurring problems.
The same principle applies to individual planning. Instead of setting a broad objective such as becoming more organized, someone could create a daily schedule, establish priorities, and review unfinished tasks at the end of each week.
It Improves the Use of Resources
Time, money, staff, and information are limited resources. Effective management helps determine where those resources are most useful and which activities deserve less attention.
This does not necessarily mean cutting every expense or trying to complete every task faster. Sometimes the better decision is to spend additional time checking important information, training a team member, or improving a process that repeatedly causes problems.
The goal is to make resource allocation intentional rather than reactive.
It Supports Better Decisions
Strong management encourages people to consider evidence, alternatives, limitations, and possible consequences before acting. This becomes particularly important when a decision involves uncertainty.
For instance, a manager considering a new business service should examine customer demand, operating costs, available staff, and potential challenges. A decision based only on enthusiasm may overlook practical constraints.
A structured decision-making process does not remove uncertainty. It makes the reasoning behind a decision easier to understand and review.
Essential Management Tips ftasiatrading Readers Can Apply
The following principles offer a practical starting point for anyone seeking better organization and more disciplined decision-making.
1. Set Clear and Measurable Objectives
Begin by identifying the result you want to achieve. Broad ambitions can provide motivation, but specific objectives make planning and evaluation more practical.
A useful objective includes a defined outcome, a reasonable timeframe, and a way to measure progress. For a business, this might involve improving delivery accuracy, organizing customer records, or shortening an unnecessarily complicated workflow.
Avoid creating too many priorities at once. When everything is treated as urgent, important work can easily be neglected.
Review your objectives periodically and adjust them when circumstances change. Changing a plan in response to new information is not necessarily a failure; it can be a sign of responsible management.
2. Create a Written Plan Before Taking Action
A written plan turns general intentions into manageable steps. It can identify required resources, responsibilities, deadlines, possible obstacles, and the conditions under which a plan should be reconsidered.
For routine business activities, a plan might specify how orders are received, checked, processed, and delivered. For a personal project, it could divide a large task into smaller stages with clear completion criteria.
In trading-related education, planning should also include understanding the product or market involved, identifying possible losses, and deciding what information is needed before making a financial decision.
A plan should be detailed enough to guide action without becoming so complicated that nobody follows it. Simple, usable procedures are often more valuable than elaborate documents that remain unread.
3. Prioritize Tasks According to Importance
Not every task contributes equally to a goal. Some activities directly affect customers, deadlines, or essential operations, while others can wait.
One practical approach is to divide tasks into four categories:
- Important and urgent: address these promptly.
- Important but not urgent: schedule dedicated time for them.
- Urgent but less important: simplify, delegate where appropriate, or handle efficiently.
- Neither important nor urgent: consider postponing or removing them.
This method helps prevent the workday from becoming a sequence of interruptions.
Managers should also distinguish between genuine urgency and pressure created by poor planning. When the same type of task repeatedly becomes an emergency, the underlying process may need improvement.
4. Maintain Consistent Records
Reliable records make it easier to understand what happened, why it happened, and what should change next time.
Businesses can record expenses, sales, customer concerns, project progress, and operational errors. Individuals can maintain task lists, learning notes, or project journals.
For trading-related activities, records may include the reasoning behind a decision, relevant market conditions, costs, the planned level of exposure, and the eventual result. Such records can help identify patterns in decision-making without assuming that previous results predict future outcomes.
Records are most useful when they are accurate, understandable, and reviewed regularly. Collecting information without examining it rarely produces meaningful improvement.
5. Review Performance Instead of Relying on Impressions
People often remember unusually successful or disappointing experiences more clearly than ordinary ones. This can make overall performance seem different from what the records actually show.
A regular review helps replace impressions with a more balanced assessment.
For a business, useful questions include whether deadlines were met, customers experienced recurring problems, expenses remained within budget, and processes became easier to follow.
For personal development, a review might examine whether planned tasks were completed and which distractions caused delays.
In trading education, performance should be evaluated across an appropriate body of records while accounting for costs, changing market conditions, and risk. A single successful result does not establish that a method is reliable, just as one disappointing result does not automatically explain why a decision was made.
The purpose of a review is to learn, not merely to assign blame or celebrate a favorable outcome.
Building Stronger Business and Team Management
Management becomes more complex when several people share responsibilities. Individual organization remains important, but teams also need clear communication, agreed procedures, and an understanding of who is responsible for each outcome.
6. Communicate Expectations Clearly
Unclear instructions can lead to duplicated work, missed deadlines, and unnecessary disagreements. Managers should explain the expected result, relevant constraints, available resources, and deadline when assigning a task.
For example, telling an employee to improve a customer report leaves considerable room for interpretation. Explaining which information is missing, what the report must include, and when it is needed gives the employee a clearer starting point.
Communication should also work in both directions. Team members need a reasonable way to ask questions, raise concerns, and explain obstacles before they become serious problems.
7. Assign Responsibilities and Establish Accountability
Every important task should have an identifiable owner. Collaboration can involve several people, but responsibility for coordinating the final result should remain clear.
A simple responsibility system identifies the person leading the task, anyone contributing to it, the deadline, and the criteria for completion.
Accountability should focus on commitments and outcomes rather than constant supervision. Managers can agree on appropriate progress updates while giving employees enough independence to complete their work.
When a task fails, the first step should be to understand what happened. The cause might be an unclear instruction, inadequate training, unrealistic timing, or a process that needs improvement. Addressing the underlying issue is more useful than automatically blaming an individual.
8. Build Repeatable Processes
Repeated activities should not require people to reinvent the method every time. Checklists, templates, and standard operating procedures can reduce avoidable mistakes and make training easier.
A basic procedure should explain the steps involved, the expected result, any important checks, and what to do when something goes wrong.
For instance, a business that frequently receives incomplete customer orders could introduce a short verification checklist before processing each order. The team could then review whether the checklist reduces errors.
Processes should remain flexible enough to accommodate legitimate exceptions. A procedure is meant to support good work, not prevent sensible judgment when circumstances differ.
9. Encourage Constructive Feedback
Feedback allows people to identify problems that may not be obvious to management. It can also reveal whether an existing process is creating unnecessary work.
Effective feedback is specific, respectful, and focused on observable behavior or results. Instead of saying that a team member is careless, a manager can explain which information was missed, what effect it had, and how the checking process could improve.
Managers should also invite feedback about their own decisions. A workplace where people can raise reasonable concerns is better positioned to identify weaknesses before they become recurring issues.
Risk Management in Trading-Related Activities
Risk management deserves special attention when the keyword is interpreted in a financial or trading context. Market prices can change unexpectedly, and no planning method can remove the possibility of financial loss.
The aim is not to predict every movement. It is to understand uncertainty, limit avoidable exposure, and avoid making decisions that could create consequences beyond what a person or organization can reasonably handle.
10. Understand Potential Loss Before Making a Decision
Before considering any financial transaction, it is important to understand what could go wrong.
Relevant questions include what factors could affect the outcome, how much money could be lost, whether additional costs apply, and whether the financial commitment is appropriate for the circumstances.
People should also understand the difference between an advertised opportunity and a verified financial service. A website discussing markets or offering educational articles is not automatically a regulated broker, investment adviser, or trading platform.
Claims about safety, reliability, regulation, or potential returns should be independently verified rather than accepted simply because they appear in promotional material.
11. Avoid Decisions Driven by Emotion
Excitement, frustration, and fear can influence judgment. In trading-related situations, a sudden price movement or a disappointing result may create pressure to act immediately.
A predefined decision process can help reduce impulsive responses. This might involve pausing to review the available information, checking whether the original reasoning remains valid, and considering whether new information changes the assessment.
The same principle applies to ordinary business management. A customer complaint or unexpected expense may require prompt attention, but an immediate reaction is not always the most effective response.
Discipline does not mean refusing to change a decision. It means making changes for understandable reasons rather than reacting automatically to emotion.
12. Be Careful With Leverage
Leverage allows a person to control a larger financial position than the money initially committed. Although it can magnify gains, it can also magnify losses and introduce additional costs or requirements.
Its effects can be difficult to manage, especially for people who do not fully understand the product involved. Depending on the arrangement, losses and obligations may develop more quickly than expected.
A responsible approach begins with understanding the terms, the maximum potential exposure, and the consequences of adverse price movements. Avoiding products that are not fully understood is a sensible safeguard.
There is no universal position size or risk percentage that guarantees safety. Appropriate financial decisions depend on the specific product, its rules, the individual’s circumstances, and the possibility of losing money.
13. Keep Financial and Operational Records Separate
Clear records help people distinguish operating expenses, personal spending, available funds, and money committed to particular activities.
For a business, this may mean maintaining organized accounting records and regularly reconciling transactions. For an individual studying financial markets, it can mean recording costs and results separately instead of relying on memory.
Good record keeping also supports transparency. It makes it easier to identify discrepancies, understand obligations, and explain how a decision was reached.
Records containing sensitive financial information should be stored securely and shared only with appropriate people.
Using Technology to Improve Management
Digital tools can make management more organized, but they work best when they address a clearly identified problem.
14. Choose Tools That Solve Real Problems
Task managers, spreadsheets, accounting applications, communication systems, and reporting dashboards can help organize work. The right choice depends on the activity, budget, privacy requirements, and technical needs.
Before adopting a tool, consider whether it will reduce repeated work, improve accuracy, or make important information easier to access.
For example, a small business may benefit from a shared task board if employees frequently lose track of deadlines. A complicated enterprise system may offer little value if the business only needs a straightforward checklist.
When evaluating a platform associated with FTAsiaTrading, distinguish between features that are publicly documented and features that are merely claimed. Do not assume that a service provides automated trading, verified market data, account protection, or specialist support unless those capabilities have been confirmed.
15. Use Automation Carefully
Automation can handle repetitive activities such as sending reminders, organizing information, and preparing routine reports.
However, automated processes can repeat errors just as efficiently as they repeat correct actions. Incorrect settings, outdated information, and unexpected exceptions may produce misleading results.
Before relying on automation, test the process, review its outputs, and establish a way to identify failures. Important decisions should receive appropriate human oversight, particularly when financial consequences or sensitive information are involved.
Automation should make a sound process more efficient rather than conceal weaknesses in the process itself.
16. Protect Information and Access
Management includes protecting the information needed to run a business or manage an account.
Useful precautions include using strong, unique passwords, enabling multifactor authentication where available, keeping software updated, and limiting access according to responsibilities.
Be cautious of unsolicited messages requesting passwords, verification codes, payment, or remote access to a device. Check the identity of a service independently before sharing sensitive information.
If a platform handles financial information, examine its identity, applicable regulatory status, privacy practices, and account-security arrangements before deciding whether to use it. A professional-looking website alone does not establish that a service is trustworthy.
Common Management Mistakes to Avoid
Even a carefully designed management approach can fail when everyday habits undermine it. Recognizing common mistakes makes improvement more practical.
Trying to Manage Everything at Once
Too many simultaneous priorities divide attention and make it harder to complete important work. A better approach is to identify the most important objectives, schedule realistic workloads, and postpone activities that do not need immediate attention.
Ignoring Small Problems
Repeated minor errors may reveal a larger weakness in a process. Missing information, frequent customer complaints, or recurring delays deserve investigation before they become more disruptive.
Managers should look for patterns instead of treating every incident as unrelated.
Confusing Activity With Progress
A full calendar does not necessarily indicate effective work. Meetings, reports, and messages are useful only when they contribute to a meaningful objective.
Review whether each recurring activity supports a decision, improves coordination, or produces a required outcome. Remove unnecessary steps when doing so will not compromise quality or accountability.
Changing Plans Without Reviewing Evidence
Adaptability is important, but changing direction after every setback can prevent a strategy from being evaluated fairly.
Before changing a plan, identify what new information has emerged, whether the original assumptions remain reasonable, and what the consequences of changing course might be.
In uncertain environments, it is also important to recognize that a favorable outcome does not always prove a decision was sound, and an unfavorable outcome does not automatically prove it was poorly reasoned.
Trusting Unsupported Promises
Claims of guaranteed profits, effortless growth, secret strategies, or risk-free financial opportunities deserve particular caution.
Management techniques can improve organization and decision quality, but they cannot eliminate business uncertainty or guarantee market outcomes. Evaluate claims using credible evidence, clear terms, and independent verification.
How to Build a Practical Management Routine
Understanding management principles is useful, but applying them consistently is what makes them valuable. A manageable routine can help individuals and teams turn broad ideas into everyday habits.
Start Each Week With Planning
At the beginning of the week, identify the most important objectives, deadlines, and potential obstacles. Decide which tasks require immediate attention and which can be scheduled for later.
For a business, this may involve reviewing customer commitments, available resources, and unfinished projects. For someone studying financial markets, it may involve reviewing educational goals, organizing research, and understanding upcoming events that could affect market conditions.
The purpose is to begin with a clear direction rather than responding to every new demand without considering its importance.
Use Short Daily Reviews
A brief daily review helps keep priorities visible. Check completed tasks, identify anything delayed, and decide what needs attention next.
If a task remains unfinished, determine whether the problem involves insufficient time, missing information, competing priorities, or an unrealistic deadline. This makes it easier to choose an appropriate response.
Daily reviews should remain simple. If reviewing progress becomes more time-consuming than the work itself, the process needs to be streamlined.
Review Results at the End of the Month
Monthly reviews provide an opportunity to examine broader patterns. Look at progress toward goals, recurring problems, resource use, and whether existing procedures remain appropriate.
Avoid measuring success through a single number alone. A business may increase sales while experiencing higher costs, for example, so revenue by itself may not provide a complete picture.
Similarly, financial or trading-related results should be considered alongside costs, risk, and the conditions in which decisions were made.
The most useful review ends with a small number of practical improvements rather than an overwhelming list of changes.
How Beginners Can Apply Management Tips ftasiatrading
Beginners do not need complicated software or an extensive management framework to get started. A simple system that encourages consistency is often a better starting point.
First, define the objective. Understand what you want to manage and what a successful result would look like.
Second, create a written plan. Identify the necessary steps, available resources, possible obstacles, and information you still need.
Third, maintain records. Use a notebook or suitable digital tool to record important decisions, progress, and mistakes.
Fourth, review what happened. Compare the actual outcome with your original expectations and consider what could be improved.
Finally, make gradual adjustments. Change one or two important habits at a time so that you can evaluate whether the changes are useful.
For readers interested in trading, education should come before committing money. Learn the relevant terminology, understand the product and its risks, and verify the status of any service you are considering. Simulated practice can help develop familiarity with a process, although simulated outcomes do not necessarily reflect real trading conditions.
It is also important to remember that learning management techniques is not the same as receiving personalized financial advice. Major financial decisions should take account of individual circumstances and, where appropriate, guidance from a suitably qualified professional.
Measuring Whether Your Management Approach Is Working
A management system should be reviewed according to the results it is designed to support. Choosing a few relevant measures makes it easier to identify improvements without collecting unnecessary information.
| Management area | What to review | Why it matters |
|---|---|---|
| Planning | Progress against defined objectives | Shows whether priorities are realistic |
| Productivity | Completed work and recurring delays | Helps identify inefficient processes |
| Communication | Unresolved questions and handoff errors | Reveals coordination problems |
| Financial control | Costs, commitments, and available funds | Improves financial visibility |
| Risk management | Exposure, exceptions, and control failures | Helps identify avoidable vulnerabilities |
| Learning | Recurring mistakes and corrective actions | Supports continuous improvement |
These measures should be adapted to the activity being managed. A small business does not need the same reporting system as a large organization, and an individual learning about markets does not need an institutional trading dashboard.
The important question is whether the information helps someone make a better decision. If a measure does not support a useful action, it may not deserve the time required to maintain it.
Conclusion
Management Tips ftasiatrading is best approached as a topic about structured planning, responsible decision-making, organization, and disciplined management in business and trading-related contexts.
The strongest management habits are practical: establish clear objectives, create written plans, maintain accurate records, communicate responsibilities, review results, and respond to new information thoughtfully. Technology can support these habits, but it cannot replace sound judgment or guarantee favorable outcomes.
Readers should also distinguish general educational guidance from verified information about a specific platform or company. The keyword itself does not establish a service’s ownership, regulatory status, capabilities, or reliability.
Ultimately, effective management is an ongoing process of planning, action, evaluation, and improvement. By building that process around clear goals and realistic expectations, individuals and organizations can make their work more organized and their decisions easier to assess.
Frequently Asked Questions
1. What are Management Tips ftasiatrading?
Management Tips ftasiatrading is a search term associated with management practices relevant to business organization, trading-related activities, planning, and decision-making. The most useful principles include maintaining clear objectives, recording decisions, reviewing performance, and understanding risk.
2. What is the most important management tip for beginners?
Start with a clear plan. Define the objective, identify the steps required, establish realistic limits, and decide how you will evaluate progress. A simple plan that is followed and reviewed is more useful than a complicated plan that is ignored.
3. How can management improve decision-making?
Management improves decision-making by encouraging people to gather relevant information, consider alternatives, assess potential consequences, and review results. These habits help reduce avoidable errors, although they cannot eliminate uncertainty.
4. Is FTAsiaTrading a verified trading platform?
The keyword alone does not establish that FTAsiaTrading is a regulated trading platform or financial service. Anyone considering a service under this name should independently verify its legal identity, regulatory status where applicable, terms, and security arrangements before sharing information or committing money.
5. How does risk management relate to trading?
Risk management involves identifying potential losses, understanding exposure, and setting appropriate limits before making a financial decision. It also includes keeping accurate records and avoiding commitments whose potential consequences are not understood.
6. Can technology make management more effective?
Yes. Appropriate digital tools can help organize tasks, maintain records, automate routine work, and make performance information easier to review. Their usefulness depends on selecting suitable tools and checking that the information and processes remain accurate.
7. How often should management plans be reviewed?
Daily reviews can help manage immediate tasks, weekly reviews can clarify priorities, and monthly reviews can reveal broader patterns. The appropriate frequency depends on the complexity of the activity and how quickly circumstances change.
8. Can good management guarantee business or trading success?
No. Effective management can support better organization, more consistent decisions, and stronger awareness of risk, but it cannot guarantee profits or prevent every business problem. External conditions, uncertainty, and factors beyond a person’s control continue to matter.
RELATED POST: What Is a Target Company URL? A Complete Guide to Finding and Verifying Business Websites