
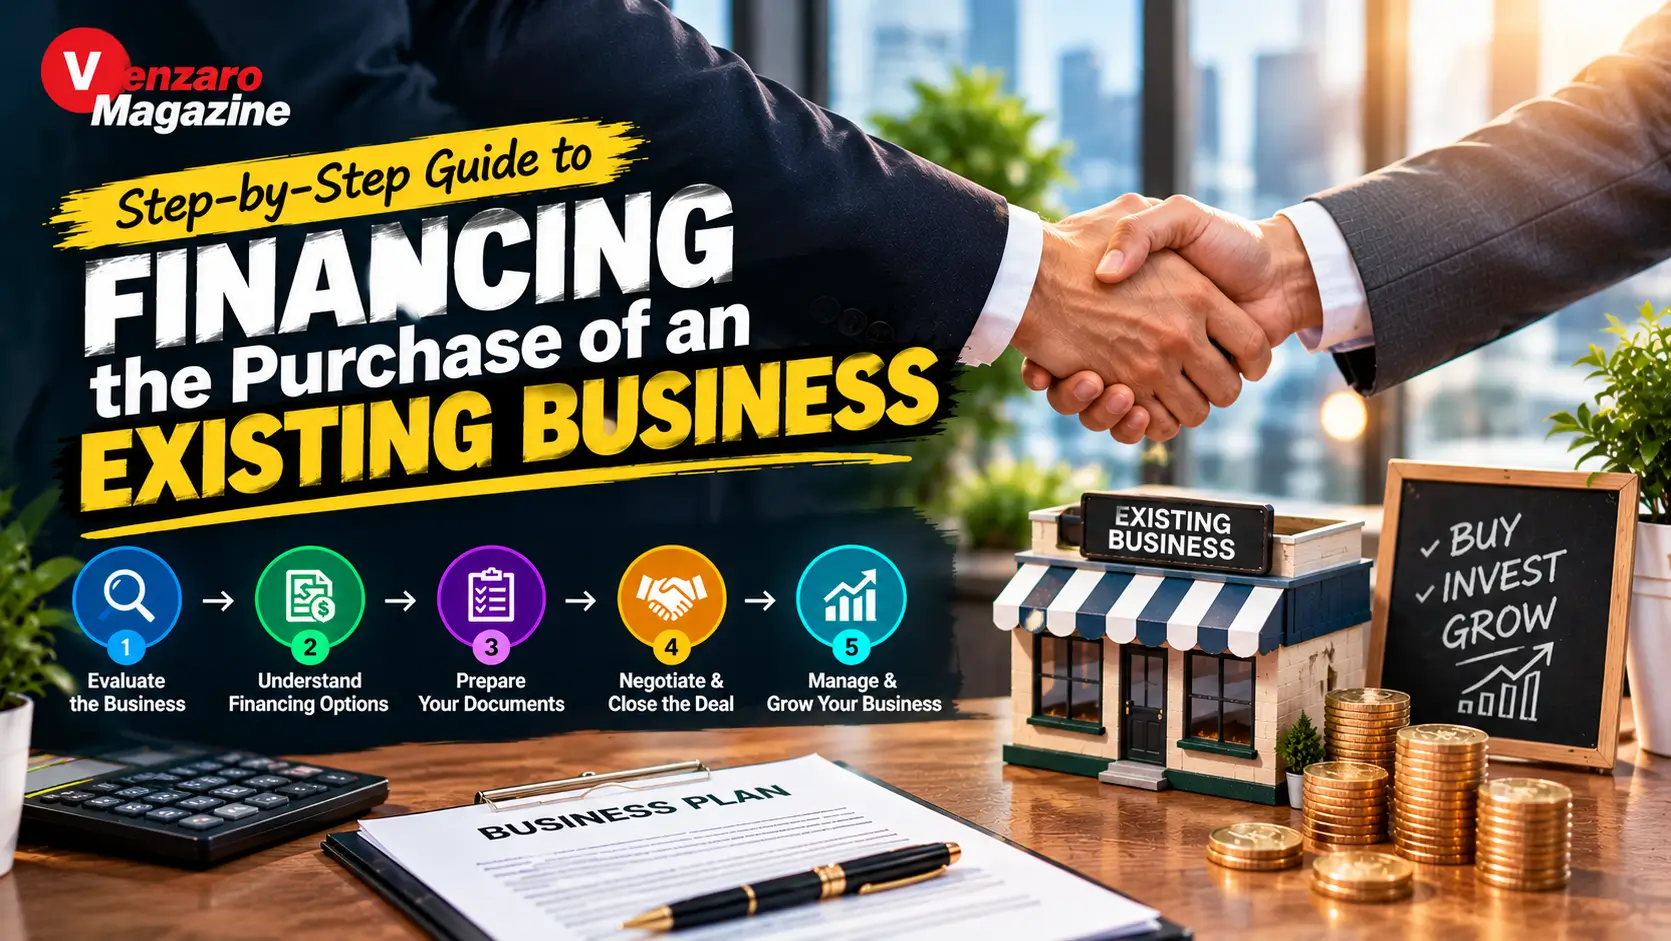
Buying an existing business can offer a practical route into entrepreneurship. Instead of starting from scratch, a buyer may acquire an established customer base, existing products or services, trained employees, equipment, supplier relationships, and a recognizable market presence. However, purchasing a business requires careful financial planning, particularly when the buyer cannot cover the entire purchase price with personal savings.
A step-by-step guide to financing the purchase of an existing business helps prospective owners understand how to estimate the total investment, compare funding options, approach lenders, negotiate payment terms, and prepare for the responsibilities that follow an acquisition. The objective is not simply to secure enough money to complete the transaction. It is to structure the purchase so that the business can continue operating and meet its financial obligations after the ownership changes.
Financing an acquisition can involve personal capital, commercial loans, seller financing, investor contributions, or a combination of different sources. The right approach depends on the purchase price, the business’s financial performance, the buyer’s creditworthiness, available collateral, and the level of risk both parties are prepared to accept.
This guide explains the process in practical stages, helping first-time entrepreneurs and experienced buyers understand the decisions involved before committing to an acquisition.
Why Financing Matters When Buying an Existing Business
An established business may have a history of revenue and operating expenses, but that does not automatically make it a safe investment. Its profitability, outstanding liabilities, customer relationships, and future prospects all influence how much a buyer should pay and how the acquisition should be funded.
Financing affects more than the ability to complete the purchase. It also determines how much cash remains available for inventory, payroll, rent, marketing, maintenance, and unexpected expenses.
For example, a buyer who uses nearly all available funds to purchase a company may struggle to cover ordinary operating costs during the first few months. Even a business with a healthy sales history can experience temporary disruptions after a change in ownership.
A suitable financing structure should therefore account for three separate needs: the acquisition price, the costs of completing the transaction, and the working capital required to operate the business afterward.
Buyers should also distinguish between revenue and cash flow. Revenue represents money earned from sales, while cash flow reflects the timing of money entering and leaving the business. A company can report strong sales and still experience difficulties paying bills if customers pay late or operating expenses rise.
Understanding these differences before borrowing helps buyers make more informed decisions and avoid taking on obligations that the acquired business may struggle to support.
Step 1: Define Your Budget and Calculate the Total Acquisition Cost
The first step is to determine how much the acquisition will realistically cost. The advertised purchase price is only one part of the financial commitment.
Depending on the transaction, additional expenses may include legal services, accounting support, valuation work, lender fees, insurance, licenses, lease deposits, inventory adjustments, and necessary equipment repairs. Some buyers may also need to invest in technology upgrades, employee training, or changes to branding and marketing.
Create a detailed acquisition budget before approaching lenders. Divide the costs into three categories:
- Purchase costs: The agreed price for the shares, assets, or other interests being acquired.
- Transaction costs: Professional fees, financing charges, due diligence expenses, and other closing costs.
- Post-purchase funds: Working capital, initial operating expenses, and a reasonable reserve for unexpected problems.
The distinction matters because a lender may not finance every expense associated with the acquisition. Some costs may need to be covered through personal funds or another funding source.
Determine how much you can contribute
Calculate the amount you can invest without putting essential personal finances at unnecessary risk. Consider available savings, existing financial commitments, and any funds that must remain untouched for emergencies.
A larger personal contribution can reduce the amount borrowed and may make the proposal more attractive to some lenders. However, contributing more cash is not always the best decision if it leaves the buyer without sufficient reserves.
The aim is to strike a balance between a manageable loan and enough liquidity to handle the unexpected.
Estimate the business’s ability to support debt
Before deciding how much to borrow, examine whether the business can generate enough dependable cash flow to cover operating costs, loan repayments, taxes, and other obligations.
Use conservative assumptions rather than relying entirely on the seller’s most optimistic projections. If the business experiences seasonal fluctuations, customer concentration, or rising supplier costs, include those risks in the estimate.
A purchase may appear affordable at the asking price but become financially difficult when repayment obligations are considered.
Step 2: Evaluate the Business Before Choosing Financing
Lenders and buyers both need to understand what makes the business financially viable. A business should not be purchased solely because it has operated for several years or appears popular with customers.
Review its financial records and investigate whether reported performance is sustainable.
Important documents may include:
- Profit-and-loss statements for recent years.
- Balance sheets showing assets, liabilities, and equity.
- Cash flow statements and bank records.
- Business tax returns, where applicable.
- Accounts receivable and accounts payable records.
- Inventory reports and equipment schedules.
- Details of existing loans, leases, and other contractual obligations.
The exact documents required will depend on the business, jurisdiction, and financing arrangement.
Examine earnings quality
Look beyond headline revenue and advertised profit. Determine whether reported earnings reflect ordinary operations and whether the business depends heavily on the current owner’s personal relationships, unpaid labor, or unusual one-time income.
If the seller claims that certain personal or discretionary expenses can be removed after the acquisition, ask an accountant to assess whether those adjustments are reasonable. Not every expense described as discretionary will disappear when ownership changes.
Also consider whether the business will need additional spending to replace aging equipment, retain key employees, or maintain its existing customer base.
Conduct financial and legal due diligence
Due diligence means investigating the business before completing the purchase. Financial reviews should be accompanied by appropriate legal, operational, and commercial checks.
Depending on the transaction, these may include verifying ownership of assets, checking outstanding debts, reviewing contracts, examining tax obligations, confirming licenses, and assessing any legal disputes.
The buyer should also understand whether the proposed deal involves purchasing company shares or selected business assets. These structures can have different legal, tax, and liability consequences.
Professional advice is particularly important when the transaction involves complicated liabilities or contractual restrictions. Discovering a serious problem before signing a binding agreement is generally easier than addressing it after the acquisition.
Step 3: Determine How Much Financing You Need
Once the purchase price and financial condition of the business are clearer, calculate the amount that must be funded.
The basic calculation is:
Total funding requirement = purchase price + transaction costs + initial working capital − available funds allocated to the purchase.
This is a planning formula rather than a guarantee that every expense can be included in a particular loan.
For example, suppose a business has an agreed purchase price of $400,000. The buyer estimates $20,000 in transaction costs and wants $40,000 available for initial working capital. If the buyer contributes $100,000 toward the acquisition and related expenses, the remaining funding requirement is $360,000.
Illustrative acquisition budget
Business purchase price
$400,000
Transaction costs
$20,000
Initial working capital
$40,000
Total estimated requirement
$460,000
Buyer’s contribution
−$100,000
Remaining funding requirement
$360,000
Illustrative figures only. Actual costs, eligible financing expenses, and required cash contributions vary.
This estimate gives the buyer a starting point for discussing financing. It should be updated when due diligence reveals additional costs or the purchase price changes.
Avoid treating the entire funding requirement as a loan request before understanding the available financing products. Some expenses may need to be funded separately, and some lenders may require a specific equity contribution.
Step 4: Compare the Main Business Acquisition Financing Options
There is no single financing method suitable for every business purchase. Buyers should compare multiple options and consider how each one affects repayments, ownership, control, collateral, and financial flexibility.
Traditional bank loans
Commercial bank loans can provide funding for qualifying business acquisitions. Approval commonly depends on the buyer’s financial position, the business’s earnings, the amount of the down payment, available collateral, and the lender’s assessment of risk.
A bank may request detailed financial statements, tax records, a business plan, personal financial information, and a proposed repayment structure.
Advantages: Bank financing may offer structured repayment terms and allow the buyer to retain full ownership if no equity investor is involved.
Limitations: Approval can be demanding, and the lender may require collateral, guarantees, or a meaningful personal contribution. The process can also take time.
Compare the annual percentage cost where available, fees, repayment period, prepayment conditions, and default provisions rather than choosing a loan solely because its initial interest rate looks attractive.
Government-backed acquisition financing
Some countries offer lending programs, guarantees, or other support for qualifying small businesses. In the United States, certain Small Business Administration-backed loan programs may be available for eligible ownership changes and acquisitions through participating lenders.
These programs have specific eligibility rules, documentation requirements, permitted uses, and lender conditions. Government backing does not mean every acquisition will qualify or that the government directly provides every loan.
Buyers should confirm current program requirements with an authorized lender or the relevant government agency before building their purchase plan around a particular scheme.
Seller financing
Seller financing occurs when the seller agrees to receive some of the purchase price over time rather than receiving the entire amount at closing.
For example, a buyer might pay part of the agreed price upfront and sign an agreement to repay the seller the remaining balance according to a defined schedule.
This arrangement can reduce the amount of immediate third-party financing required. It may also help bridge a gap between the buyer’s available funds and the seller’s desired price.
However, seller financing is not automatically inexpensive or flexible. The agreement should clearly state the interest rate, payment schedule, maturity date, default consequences, security arrangements, and any restrictions on early repayment.
If a bank loan is also involved, the seller-financed portion may need to comply with the senior lender’s requirements. Buyers should not assume that a seller will agree to postpone payments or accept a lower priority claim without negotiation.
Private investors and equity partners
An investor may contribute capital in exchange for an ownership interest, profit participation, or another negotiated financial arrangement.
This can reduce the amount of debt the buyer needs to take on. Unlike a conventional loan, an equity investment does not necessarily require fixed monthly principal and interest payments.
The trade-off is shared ownership and potentially shared decision-making. Investors may expect voting rights, access to financial information, influence over strategy, or a defined route to eventually selling their stake.
Any investment agreement should establish ownership percentages, responsibilities, distributions, decision-making authority, dispute resolution, and exit arrangements.
Asset-based and equipment financing
Some transactions involve valuable equipment, vehicles, inventory, or other assets that may support a separate financing arrangement.
Asset-based lending generally depends on eligible assets and the lender’s valuation and lending criteria. Equipment financing may be appropriate when identifiable machinery or vehicles are a major part of the purchase.
These options are not interchangeable with general acquisition loans. A lender may finance only specified assets rather than the entire business purchase, and the assets may serve as collateral.
Buyers should also confirm that the seller has the legal right to transfer the assets and disclose any existing security interests.
Combining financing methods
A buyer may use a combination of personal savings, a commercial loan, seller financing, and outside investment. Combining sources can make a transaction possible when no single source covers the full cost.
However, more funding sources also mean more agreements, repayment obligations, and potential conflicts. The buyer should understand which lenders have priority, what happens after a default, and whether one financing agreement restricts another.
The best structure is not necessarily the one that raises the most money. It is the one that supports the acquisition while leaving the business financially capable of operating.
Step 5: Prepare a Strong Financing Proposal
Once the funding options have been identified, prepare a clear proposal explaining what you intend to purchase, how much money you need, and how you expect to repay it.
Lenders are assessing more than the purchase price. They want to understand the commercial purpose of the transaction, the buyer’s ability to manage the business, the quality of the financial information, and the risks that could affect repayment.
A well-organized financing proposal generally includes the following elements.
A clear business overview
Describe the business, its products or services, target customers, operating history, market position, and main sources of revenue. Explain why the acquisition is commercially attractive without relying on unsupported claims about future growth.
A realistic financial forecast
Prepare projections covering revenue, operating expenses, cash flow, debt repayments, taxes, and planned investment. Explain the assumptions behind the figures, including expected changes after the ownership transfer.
Create a conservative scenario in which revenue declines, costs increase, or an important customer leaves. If the business would struggle to meet repayments under modestly unfavorable conditions, reconsider the amount borrowed or the proposed purchase price.
Evidence of your financial position
Be ready to provide information about your personal contribution, existing debts, credit history where relevant, available collateral, and other financial commitments.
Requirements differ between lenders and countries. Some financing arrangements rely heavily on business cash flow, while others place greater emphasis on personal guarantees or security.
A clear repayment strategy
Explain how the business will generate the cash needed to meet its obligations. Avoid presenting an optimistic growth forecast as the only way the loan could be repaid.
A lender may request further documents, clarification, or changes to the proposed structure. Responding promptly and keeping all financial figures consistent can help prevent unnecessary delays.
Step 6: Improve Your Eligibility Before Applying
Buyers can strengthen their financing applications by addressing weaknesses before submitting a formal request.
Start by reviewing your credit history and correcting inaccurate information where possible. Reduce avoidable personal debt if doing so is financially sensible, organize evidence of your available funds, and prepare explanations for any unusual financial transactions.
Your professional background can also matter. Experience managing employees, overseeing budgets, serving customers, or working in the same industry may help demonstrate that you understand the business you intend to acquire.
If you lack direct experience, explain how you will address the gap. A qualified manager, experienced operating partner, structured handover, or targeted training may form part of the plan.
The business itself should also be prepared for scrutiny. Accurate bookkeeping, consistent financial reporting, documented customer contracts, and a clear inventory of assets can make it easier to evaluate the proposed acquisition.
Avoid submitting applications based on inflated earnings or incomplete information. If the seller’s figures cannot be reconciled with available records, resolve the discrepancy before relying on those figures in a financing proposal.
Finally, compare lenders rather than accepting the first preliminary offer. Ask about the total borrowing cost, required contribution, collateral, personal guarantees, repayment flexibility, and expected completion timeline.
Step 7: Negotiate the Purchase Price and Financing Terms Together
Financing and purchase negotiations should be treated as connected parts of the same transaction.
A seller may have a firm view of what the business is worth, but the buyer must assess whether the price is justified by its financial performance, assets, liabilities, and future prospects.
An independent valuation can help establish a reasonable range. Depending on the business, the assessment may consider earnings, comparable transactions, assets, market conditions, and the risks associated with the company’s future performance.
Consider the structure of the deal
The purchase price may be negotiated alongside payment timing, the treatment of inventory, outstanding liabilities, working capital, and the transfer of important contracts.
A lower purchase price does not automatically produce a better deal if the business requires substantial repairs or investment immediately after closing. Similarly, a higher price may be difficult to justify if earnings depend on the seller’s personal involvement.
Some transactions include a deferred payment or an earn-out, under which part of the price depends on specified future results. Such arrangements need precise definitions, reporting rules, payment dates, and dispute procedures.
Protect yourself with appropriate conditions
Where possible, the purchase agreement should address important conditions such as satisfactory due diligence, financing approval, required third-party consents, and the transfer of essential assets or contracts.
The exact protections available depend on the applicable law and the agreement. A lawyer experienced in business acquisitions should review the documents before you become irrevocably committed.
Do not assume that a preliminary lender discussion represents final approval. Financing can still be declined or changed after the lender completes its underwriting.
Step 8: Understand Collateral, Guarantees, and Personal Risk
Some acquisition loans are secured against business assets, personal assets, or a combination of both. Other financing arrangements may have different security requirements.
Collateral is property or another asset pledged to support an obligation. A personal guarantee is a commitment under which an individual may become personally responsible for specified business debt if the borrower fails to pay.
These provisions deserve careful attention because purchasing through a limited-liability company does not necessarily eliminate personal financial exposure when separate guarantees have been signed.
Before agreeing to a guarantee, understand its scope, duration, maximum liability if limited, and the circumstances in which the lender can enforce it. Also determine whether the guarantee covers only the original loan or other obligations permitted by the documents.
If business assets are pledged as security, ask which assets are covered and what could happen if repayments are missed. Consider how enforcement might affect the company’s ability to continue operating.
Never assume that a lender will release a guarantee automatically when the business reaches a certain level of profitability. Release conditions should be discussed and documented explicitly.
Step 9: Complete Due Diligence and Secure Final Approval
A preliminary agreement is only one stage in an acquisition. Before the transaction closes, the lender and buyer may need to complete additional checks.
The lender may reassess the business’s financial position, verify the source of the buyer’s contribution, review the final purchase agreement, value collateral, and confirm that the proposed transaction meets its requirements.
The buyer should continue investigating the business during this period. Important questions include whether key employees intend to remain, whether customers can terminate contracts after a change in ownership, and whether the premises lease can be transferred.
Confirm the status of taxes, licenses, permits, insurance, supplier arrangements, outstanding disputes, and any debt that must be settled at closing.
A closing checklist can help coordinate the work of the buyer, seller, lender, accountant, and lawyer. It should identify required documents, outstanding conditions, payment instructions, transfer dates, and responsibilities for resolving remaining issues.
Avoid releasing funds before the relevant contractual conditions are satisfied and the transfer arrangements have been verified. The closing process should be coordinated by the appropriate legal and financial professionals.
Step 10: Manage Cash Flow After the Acquisition
Completing the purchase is the beginning of a new operating responsibility, not the end of the financing process.
The first months after an ownership change can bring unexpected expenses, changes in customer behavior, supplier adjustments, and operational disruptions. A business that was profitable under the former owner may perform differently under new management.
Prepare a cash flow forecast that covers at least the immediate operating period and update it regularly. Track cash receipts, payroll, supplier payments, taxes, loan installments, and other recurring obligations.
Keep business and personal finances separate. Maintain reliable bookkeeping and monitor whether actual results match the assumptions used in the acquisition plan.
If performance falls below expectations, investigate the cause early. The problem might involve delayed customer payments, higher inventory requirements, reduced sales, or expenses that were underestimated during due diligence.
Where appropriate, discuss emerging difficulties with your accountant, lender, or financial adviser before payments become overdue. Early communication may provide more options than waiting until the business is in serious financial distress.
Most importantly, avoid making major discretionary withdrawals simply because the business generates revenue. Cash must first support the company’s operating requirements and contractual obligations.
Common Mistakes to Avoid When Financing an Existing Business
Even a promising acquisition can become financially challenging when the buyer overlooks important details.
Borrowing too much: A large loan may help secure the purchase but leave insufficient cash to operate the business. Base borrowing decisions on sustainable cash flow rather than the maximum amount a lender is willing to offer.
Accepting the seller’s financial figures without verification: Request supporting records and investigate unusual adjustments. Reported profit should not be treated as guaranteed future income.
Ignoring working capital: The purchase price does not cover every cost of running the company. Budget for inventory, payroll, rent, insurance, taxes, maintenance, and payment delays.
Choosing financing based only on interest rates: Fees, loan duration, collateral, guarantees, early repayment rules, and default provisions can materially change the overall cost and risk.
Underestimating the transition: A seller’s departure may affect customer relationships, supplier negotiations, or day-to-day operations. Plan for a practical handover and determine which knowledge needs to be transferred.
Relying on unconfirmed financing: Do not commit to an acquisition on the assumption that a lender will approve the final application. Understand financing conditions and include appropriate protections in the purchase agreement.
Failing to plan for unfavorable conditions: Forecasts should consider weaker sales, rising expenses, and unexpected repairs. A transaction that works only under ideal conditions may carry excessive risk.
Avoiding these mistakes requires disciplined planning, independent verification, and a willingness to reconsider the deal when the numbers do not support it.
How to Choose the Right Financing Structure
The right financing arrangement depends on the buyer’s available capital, the business’s financial strength, the seller’s willingness to accept deferred payments, and the terms offered by lenders or investors.
A buyer with sufficient savings may prefer to contribute more personal capital to reduce borrowing. Someone with limited savings but a strong acquisition proposal may explore a combination of commercial lending and seller financing. An acquisition involving valuable equipment may also benefit from financing specifically designed for eligible assets.
Before making a decision, compare the options using the same criteria: total cost, required cash contribution, repayment schedule, security requirements, ownership implications, and flexibility if the business underperforms.
It is also important to consider the jurisdiction in which the business operates. Lending products, government support programs, tax treatment, legal protections, and acquisition procedures differ between countries. A financing structure that works well in one market may not be available or appropriate in another.
Professional advice from an accountant, business acquisition lawyer, and suitably qualified financing adviser can help identify issues that are easy to overlook. The cost of obtaining advice should be considered as part of the acquisition budget.
Ultimately, a suitable financing structure should allow the buyer to complete the purchase without placing unnecessary pressure on the company’s future operations.
Frequently Asked Questions
Can I buy an existing business without paying the full price upfront?
Yes. Depending on the transaction, you may be able to combine a personal contribution with a business acquisition loan, seller financing, or investment from a partner. The seller and lenders must agree to the proposed arrangements, and eligibility requirements will vary.
How much money should I have before buying an existing business?
There is no universal amount. Your required contribution depends on the purchase price, transaction expenses, lender requirements, available financing, and the working capital needed after closing. You should also consider keeping an appropriate cash reserve rather than committing every available dollar to the acquisition.
Is seller financing better than a bank loan?
Neither option is automatically better. Seller financing may offer flexibility and reduce the amount needed from a bank, while a bank loan may provide a more conventional repayment structure. Compare the interest rate, fees, payment schedule, security, default provisions, and any restrictions imposed by other lenders.
Can a lender finance the entire business purchase?
Some financing structures may cover a substantial portion of an acquisition, but full financing is not guaranteed. Lenders assess the transaction, business cash flow, buyer qualifications, collateral, and their own lending policies. Additional cash may be needed for transaction costs and working capital even when the purchase price is financed.
What documents are needed to obtain acquisition financing?
Common requirements include financial statements, tax returns where applicable, bank records, business valuation information, a purchase agreement or letter of intent, a business plan, and personal financial information. Exact requirements depend on the lender, the jurisdiction, and the proposed transaction.
How do lenders decide whether an acquisition is affordable?
Lenders generally assess the business’s ability to generate cash, the buyer’s financial position, the amount being borrowed, and the risks associated with the transaction. They may also consider the buyer’s experience, available collateral, credit history, and repayment projections.
Should I hire an accountant before purchasing a business?
An accountant with relevant acquisition experience can help review financial statements, assess earnings, examine cash flow, evaluate the proposed price, and identify financial risks. Legal and tax advice may also be necessary because the structure of the acquisition can affect liabilities and future obligations.
What happens if the acquired business cannot make its loan payments?
The consequences depend on the loan agreement, security arrangements, guarantees, and applicable law. The lender may have rights to enforce security, demand payment, or pursue other remedies permitted by the agreement. Buyers should understand these risks before signing and contact their lender promptly if financial difficulties arise.
How long does it take to finance the purchase of an existing business?
The timeline varies with the complexity of the transaction, lender requirements, the completeness of the financial records, due diligence, and any necessary third-party approvals. Straightforward transactions may progress faster than acquisitions involving complicated ownership structures, multiple financing sources, or unresolved legal issues. Buyers should build sufficient time into the purchase agreement.
Conclusion-Step-by-Step Guide to Financing the Purchase of an Existing Business
Financing the purchase of an existing business requires more than finding a lender willing to provide money. It involves evaluating the business, understanding its financial performance, calculating the full acquisition cost, comparing funding options, negotiating suitable terms, and protecting the buyer from avoidable risks.
A disciplined approach begins with a realistic budget and thorough due diligence. From there, buyers can assess commercial loans, seller financing, investors, and other appropriate funding methods before preparing a detailed financing proposal.
The most important consideration is whether the acquired business can support its financial obligations while continuing to operate effectively. A purchase that leaves sufficient working capital and allows for unexpected challenges is generally more sustainable than one that uses every available resource to complete the transaction.
By combining careful financial analysis, appropriate professional advice, and realistic planning, prospective owners can make better-informed decisions about acquiring an established business and preparing it for its next stage of development.
RELATED POST: What Is a Target Company URL? A Complete Guide to Finding and Verifying Business Websites